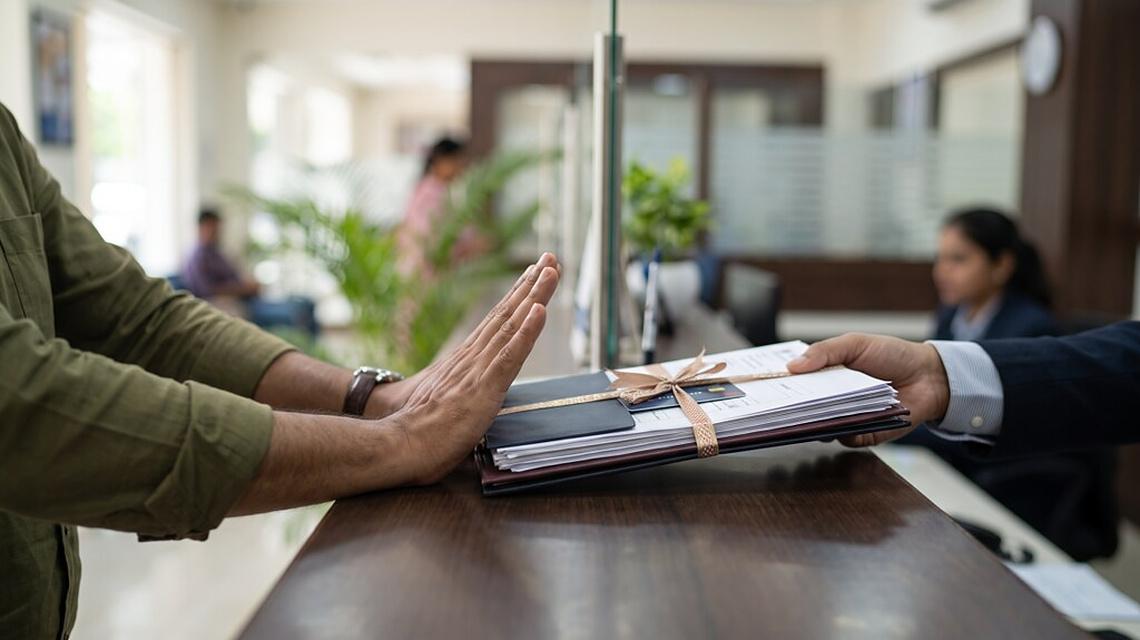
he Reserve Bank of India (RBI) has imposed stricter control on the advertising, marketing and sale of financial products through the RBI (Commercial Banks – Responsible Business Conduct) Second Amendment Directions, 2026 (amendment), which will come into force on 1 January, 2027.
The amendment expands the RBI’s framework governing promotional activities of commercial banks relating to the advertising, marketing and sale of financial products. While the RBI (Commercial Banks – Responsible Business Conduct) Directions, 2025, established broad conduct principles, the amendment introduces detailed requirements relating to customer consent, suitability assessments, sales documentation, direct selling agents (DSAs), prevention of mis-selling, advertising controls, digital practices, customer feedback and compensation.
Partner
SNG & Partners
The revised framework extends beyond the branch sales practices and addresses digital journeys, user interfaces, DSAs and direct marketing agents (DMAs), third-party payment service provider presence within bank premises, internal incentive structures, bundling practices, and post-sale remediation.
In practical terms, the RBI has moved the regulation of how products are sold into detailed, principal-level compliance obligation.
Objective: The amendment aims to make banks more responsible when dealing with customers. While the earlier
guidelines focused primarily on customer protection, the amendment establishes clear rules on advertising, customer communication, consent and prevention of mis-selling. It also makes banks accountable for employees, agents, third-party sellers and digital platforms used in the sale of financial products.
Applicability: The framework applies to most commercial banks except small finance banks, payment banks, regional rural banks and local area banks. It covers both bank products and third-party products, including insurance, mutual funds and pension schemes distributed through banks.
Customer consent, disclosures and anti-mis-selling
- Customer consent. Banks must obtain clear and explicit consent before selling any product. Customers must actively agree through methods such as signature, one-time passwords (OTPs) or digital confirmation. Hidden or pre-selected options are prohibited.
- Product disclosure. Banks must clearly explain all key details, including fees, interest rates, risks, lock-in periods and exit conditions before a customer agrees to purchase a product.
- Regulation of agents/intermediaries. Banks must monitor DSAs/DMAs, maintain a public list of such agents and ensure they follow strict conduct rules.
- Mis-selling. The amendment clearly defines mis-selling, including the sale of unsuitable products, concealment of material information and sales made without proper consent. In such cases, banks may be required to provide refunds or compensation.
- Ban on forced bundling. Banks cannot compel customers to buy third-party products along with bank products. Customers must always have the option to choose.
- Control on digital practices. The RBI has prohibited the use of “dark patterns” on digital platforms, including pre-ticked boxes or misleading urgency messages.
- Post-sale feedback. Banks must contact customers within 30 days of sale to confirm that they understood the product purchased.
The amendment significantly changes how banks manage product distribution. Compliance will require detailed policies, enhanced training programmes and stronger oversight of all sales and third-party activities.
Banks will also need to review digital platforms, marketing campaigns and incentive structures. Incentives that encourage mis-selling must be eliminated.
Implementation challenges for banks
Challenges: Banks may face several challenges while implementing these rules, including:
- Updating old systems and processes;
- Monitoring large networks of agents;
- Ensuring consistency across branches and digital channels; and
- Managing customer complaints, remediation and compensation.
Failure to address these challenges by banks could result in regulatory action and loss of customer trust.
Customer benefits from the amendment
Customer benefits: The amendment promotes fair practices through:
- Greater transparency in product information;
- Protection from mis-selling;
- Better control over financial decisions; and
- Fair treatment from banks and agents.
Banking sales reforms strengthen customer trust
The amendment represents major reforms in the banking sector. Banks must now ensure fairness, transparency and accountability at every stage of the sales process.
While implementation may require effort, the long-term result will be stronger customer trust and a healthier financial system, with customers benefiting from safer and more reliable banking services.