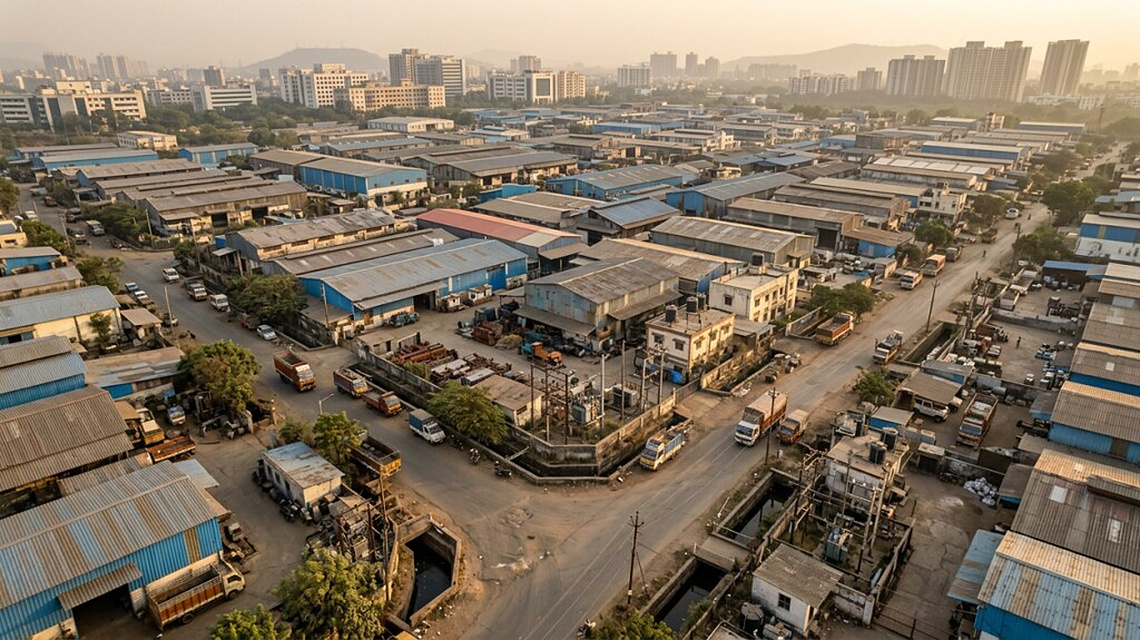
he Supreme Court has clarified a long-running dispute over property tax in the Trans Thane Creek (TTC) Industrial Area, developed by the Maharashtra Industrial Development Corporation (MIDC). In Small Scale Entrepreneurs Association & Ors v State of Maharashtra & Ors (2026), the court defined the respective roles of the Navi Mumbai Municipal Corporation and the MIDC, with implications for other industrial areas developed by statutory authorities within municipal limits.
Tax or service charge?
The MIDC acquired land under the Maharashtra Industrial Development Act, 1961, (MID Act) to develop the TTC Industrial Area, building and maintaining infrastructure, and recovering service charges from unit and plot holders. When the NMMC also sought to levy property tax on the same units, holders objected – arguing that the MIDC already charged for civic services, so the Navi Mumbai Municipal Corporation’s parallel demand was impermissible. The court’s key move was distinguishing the authority that provides civic services from the authority empowered to levy property tax – these need not be the same body.
NMMC holds taxing power
Partner
SNG & Partners
The court held that the TTC falls within the Navi Mumbai Municipal Corporation’s territorial jurisdiction; the MIDC’s development and administration of the area does not remove it from municipal limits. Crucially, the MID Act contains no provision empowering the MIDC to levy or collect property tax. That statutory power rests with the Navi Mumbai Municipal Corporation under the Mumbai Municipal Corporation Act.
The MIDC, meanwhile, remains entitled to recover charges for the infrastructure and services it provides. Such service charges do not become “tax” simply because occupants pay them – a tax is an exaction for public purposes, while a fee tracks the services actually rendered.
So the MIDC’s charges do not amount to an exercise of municipal taxing power.
Court confirms tax exemption
This is the judgment’s most significant aspect. Having confirmed the Navi Mumbai Municipal Corporation’s power to levy, the court turned to clause 7(1) of the First Schedule to the Maharashtra Regional and Town Planning Act, 1966 (MRTP Act). This clause allows exemption from municipal taxation where a development authority itself provides civic amenities, with scope for a lump-sum arrangement between the development authority and the local authority in lieu of taxes.
The court held this exemption extends to the MIDC and to unit/plot holders on MIDC-vested land, for as long as the MIDC continues providing and maintaining the relevant infrastructure. So the judgment addresses not just who can levy tax, but when that power becomes operative.
Transfer of infrastructure
Associate
SNG & Partners
The exemption from municipal taxation is not permanent. It is tied to the MIDC’s continued performance of civic functions. Once the MIDC hands over the relevant infrastructure and maintenance responsibilities to the Navi Mumbai Municipal Corporation, the exemption’s basis disappears, and the Navi Mumbai Municipal Corporation can then levy and recover property tax.
Why it matters
The ruling’s significance extends beyond the TTC:
-
- It clarifies the division between taxing power and service recovery power where development authorities operate inside municipal limits.
- The ruling modernises the legal position on municipal versus development authority taxation, offering a reference point for similar disputes.
What else matters
The court conditions the exemption on the MIDC “continuing to provide” civic amenities, but never defines what counts as a transfer, who determines it, or whether formalisation (notification/order) is required. Since infrastructure handovers are typically partial and staggered (roads but not sewage, water but not lighting), the absence of a test invites the very jurisdictional litigation the judgment sought to end.
Court separates three concepts
The Supreme Court separates three previously entwined concepts: territorial jurisdiction, taxing power and the provision of civic services. Its core message: jurisdiction to tax, responsibility to serve and entitlement to exemption are distinct questions, each requiring its own statutory analysis.
Samreen Paloba is a partner and Sara Patel is an associate at SNG & Partners